In This Article
The humanoid robot race is usually presented as a competition between machines.
Figure, Tesla, Boston Dynamics, UBTECH, Agility Robotics, Unitree and a growing number of other companies are developing robots designed to walk, manipulate objects, work alongside people and perform tasks across factories, warehouses and other environments.
But there is another race taking place underneath the one everyone can see.
It is the race to build the factories, components, materials and supply chains required to produce those robots at scale.
That distinction matters.
A humanoid robot is not simply an artificial intelligence system with arms and legs. It is a highly complex industrial product that brings together electric motors, precision gearboxes, actuators, sensors, batteries, semiconductors, power electronics, mechanical structures, software and manufacturing systems.
And many of those technologies already belong to established industries.
The question is therefore becoming less about who can demonstrate the most impressive robot and more about something considerably harder:
Who can actually manufacture enough of them?
The Humanoid Robot Supply Chain Is Being Built in Real Time
For years, humanoid robots were primarily engineering projects.
Companies built relatively small numbers of expensive prototypes, modified their hardware repeatedly and used those machines to develop increasingly capable software.
That model is changing.
Figure’s experience is one of the clearest examples.
The company says its BotQ manufacturing facility increased production of Figure 03 from one robot per day to one per hour. By April 2026, Figure said it had produced more than 350 Figure 03 robots and more than 9,000 actuators across more than ten configurations.
The significance is not simply the number of robots.
Figure says the production ramp required hundreds of suppliers to be qualified against incoming inspection requirements, more than 50 in-process inspection points and more than 80 functional verification tests for every completed robot.
Its end-of-line first-pass yield had passed 80%, while its battery line had reached 99.3%.
Those numbers reveal something that demonstrations rarely show.
Building a humanoid robot is not just an engineering problem.
It is a manufacturing problem.
Figure’s Figure 03 was designed specifically around that reality. The company redesigned much of the robot to reduce part count and assembly steps, moving away from the CNC-heavy manufacturing approach used for earlier hardware toward processes such as die casting, injection molding and stamping.
It also built a new supply chain for a product category that previously had no mature high-volume ecosystem.
Figure vertically integrated critical modules including actuators, batteries, sensors, structures and electronics, while developing a network of external suppliers for the individual components.
That is the beginning of a traditional industrial transformation: moving from making machines to making the system that can repeatedly make those machines.
The Factory Is Becoming Part of the Robot
The same transition is visible elsewhere.
UBTECH has been building dedicated manufacturing infrastructure for humanoid robots, with a factory designed for a projected annual capacity of around 10,000 units.
The significance is not whether that figure represents actual production today.
It is what the investment says about the industry’s direction.
Manufacturers are beginning to design factories around humanoid production rather than simply assembling robots inside conventional laboratories.
A factory capable of producing thousands of robots per year requires standardized components, production tooling, inspection systems, inventory management, supplier agreements and repeatable assembly processes.
Once production reaches that stage, the robot manufacturer becomes dependent on another layer of industrial companies.
That is where the real supply-chain story begins.
China Is Building on an Existing Robotics Ecosystem
China enters the humanoid race with something that cannot be created overnight: an enormous existing industrial and robotics ecosystem.
According to the International Federation of Robotics, China installed approximately 295,000 industrial robots in 2024, accounting for more than half of global installations. Its operational stock exceeded two million industrial robots, the largest national installed base in the world.
Chinese manufacturers also supplied more than 57% of the domestic industrial robot market in 2024, overtaking foreign suppliers for the first time.
That matters because the technologies overlap.
The companies producing conventional industrial robots already understand servo motors, gearboxes, motion control, machine vision, precision machining, electronics, safety systems and automated production.
Humanoid robots require many of the same capabilities, although in a considerably more demanding package.
This gives China an industrial advantage that is easy to misunderstand.
It is not simply about lower manufacturing costs.
It is about supplier density.
A robot manufacturer operating inside a large industrial ecosystem can potentially find motor manufacturers, machining companies, electronics suppliers, battery producers, tooling companies and automation integrators within the same broader manufacturing environment.
China’s existing automotive and electronics industries add another layer. Batteries, sensors, cameras, power electronics and manufacturing technologies developed for electric vehicles can often be adapted to robotics.
That does not mean China has solved humanoid robotics.
Chinese humanoids are still dealing with limitations in dexterity, precision, autonomy and economics.
But the country has something extremely valuable when a new hardware category begins to scale:
an industrial base that already knows how to manufacture complex machines in very large volumes.
The Most Important Parts May Be the Ones Nobody Sees
A humanoid robot looks like one machine.
Its manufacturing supply chain does not.
One of the most important layers is the actuation system.
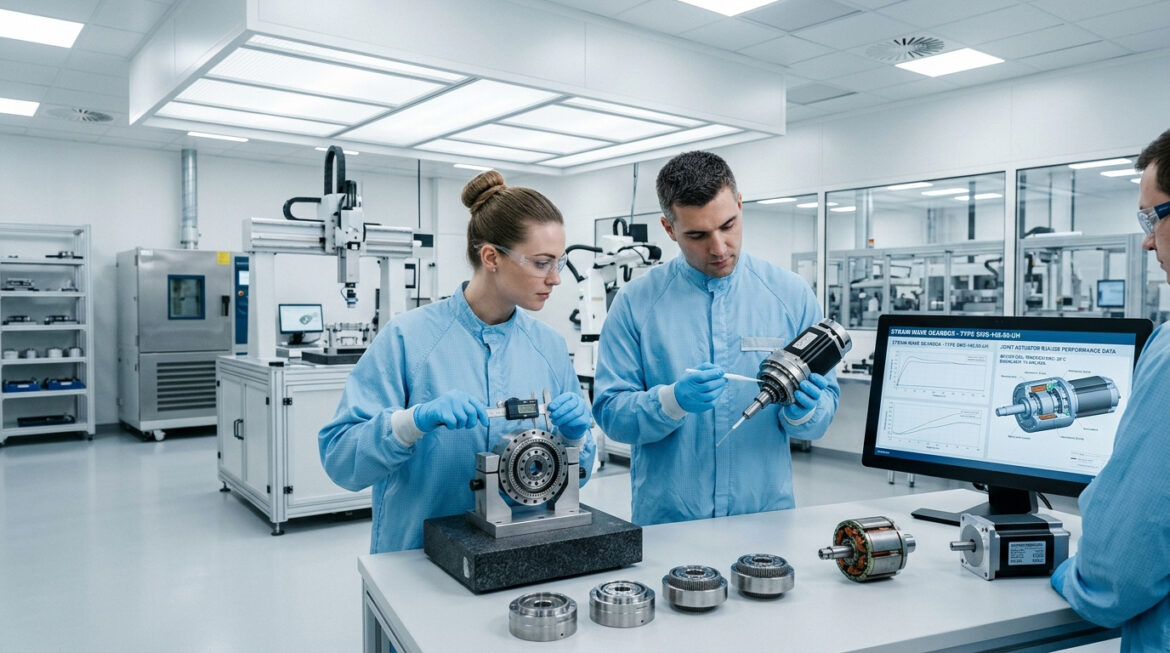
Every joint requires controlled movement. Depending on the architecture, that can involve an electric motor, gearbox, position sensing, torque sensing, bearings, power electronics and control electronics.
And a humanoid has a lot of joints.
This makes actuation one of the most important economic and engineering components of the machine.
McKinsey estimates that actuation-related systems can account for roughly 40% to 60% of humanoid robot cost, depending on architecture and assumptions.
That creates an interesting inversion.
The public discussion around humanoid robots is dominated by artificial intelligence.
But a large portion of the physical cost of the machine can be found in technologies that have existed for decades.
Motors.
Gears.
Bearings.
Precision machining.
Power electronics.
Sensors.
The humanoid revolution may therefore create enormous opportunities for companies that have never appeared on the front page of the robotics industry.
The Gearbox Problem
Precision reduction gears are a particularly revealing example.
A humanoid joint needs to generate substantial torque while remaining compact, lightweight and precise.
That is not an easy combination.
Japanese manufacturer Nabtesco has decades of experience producing precision reduction gears for industrial robots. Its technologies are already deeply embedded in the conventional robotics industry.
Nidec is moving in a similar direction, developing a portfolio for physical AI and humanoid applications that includes frameless motors, planetary gear reducers, strain-wave gear reducers and integrated sensing technologies.
German industrial supplier Schaeffler is also developing actuator technologies and strain-wave gearboxes specifically for humanoid applications.
The interesting part is not that these companies are suddenly becoming robotics startups.
They are doing almost the opposite.
The humanoid industry is beginning to pull established industrial engineering into a new market.
The robot makers need technologies that have already been refined in automotive manufacturing, machine tools and industrial automation.
But they also need those technologies adapted to a very different machine.
A humanoid cannot simply use the same actuator architecture as a fixed industrial robot.
It has to carry its own power source.
It has to move dynamically.
It has to maintain balance.
It has to interact physically with people and objects.
And every gram matters.
That creates a new market for companies capable of making existing technologies smaller, lighter, cheaper and more integrated.
The Supply Chain Is Being Invented While the Robots Are Being Built
Figure’s experience exposes another problem.
The humanoid industry does not yet have the mature supplier ecosystem that exists around automobiles.
An automotive manufacturer can draw on decades of established component standards, suppliers, qualification procedures and manufacturing processes.
Humanoid robotics is different.
The industry is still deciding what the standard architecture should look like.
Which actuator?
Which gearbox?
Which motor topology?
Which battery format?
Which tactile sensor?
Which joint architecture?
Which electronics?
Which communication system?
Which materials?
Which manufacturing process?
That uncertainty creates both risk and opportunity.
A supplier that becomes qualified early can potentially become part of a robot architecture for years.
A supplier that misses the transition may find itself outside a rapidly expanding market.
The supply chain is therefore not simply responding to humanoid robotics.
It is being shaped alongside it.
Batteries Are a Different Story
It would be tempting to describe batteries as another inevitable bottleneck.
The evidence is more complicated.
Unlike some of the precision components required by humanoids, batteries already have an enormous global industrial ecosystem behind them.
The robotics industry is becoming another customer for that ecosystem.
LG Energy Solution, for example, has developed battery products specifically for robotics applications, including humanoid, quadruped, service and logistics robots.
This is a different type of industrial transition.
The battery industry does not need to be created for humanoids.
It needs to adapt existing technologies to a new application.
The same distinction applies to many electronic components.
The question is not simply whether a component exists.
It is whether it can be produced in the required specification, quantity, price and quality — and whether production can expand quickly enough when robot orders increase.
That distinction will become increasingly important as humanoid manufacturers move from hundreds of machines toward thousands and potentially much larger volumes.
The Materials Beneath the Robot
Eventually the supply chain reaches a level that robotics companies cannot easily vertically integrate.
Raw materials.
Rare earth elements are particularly important because high-performance permanent magnets are used in electric motors.
The International Energy Agency’s analysis shows how concentrated this supply chain remains.
China accounted for approximately 60% of mined production of magnet rare earths in 2024, but its position was considerably stronger further downstream: around 91% of refining and approximately 94% of sintered permanent magnet production.
The distinction between mining and manufacturing is critical.
A country can have rare-earth deposits without controlling the supply chain.
The material must be extracted, concentrated, chemically separated, refined, converted into metals and alloys, and eventually manufactured into magnets.
The IEA identifies magnet manufacturing as a major bottleneck in efforts to diversify rare-earth supply outside China.
That is a much more precise statement than saying the world is simply “running out of rare earths.”
It isn’t.
The issue is industrial concentration.
And that matters to robotics because electric motors depend on the ability to obtain the right magnetic materials at industrial scale.
The Geopolitics of Robotics Is Already Here
The robotics supply chain therefore intersects with a much larger geopolitical issue.
China’s position in critical-mineral processing has become strategically important for industries ranging from electric vehicles and wind turbines to electronics and defence.
For robotics, the significance is straightforward.
A humanoid robot may contain dozens of motors and numerous precision electromagnetic components.
As the number of robots increases, demand for the materials and components behind those systems increases as well.
But humanoid robotics is not the only industry competing for those resources.
Electric vehicles need motors.
Wind turbines need permanent magnets.
Industrial robots need motors and drives.
Data centers need advanced electronics.
Defence systems need sensors, electronics and precision components.
Humanoid robots add another rapidly developing source of demand.
This is why the geopolitical dimension should not be reduced to “China versus America.”
The real story is the geography of the supply chain.
Mining may happen in one country.
Refining in another.
Magnet production somewhere else.
Motor manufacturing in Japan or China.
Robot assembly in the United States, China or Korea.
And the final machine may operate in a factory on the other side of the world.
The humanoid robot is therefore becoming a physical representation of global industrial interdependence.
The Semiconductor Question Is More Complicated
AI is obviously central to the humanoid robot.
Modern humanoids need computer vision, perception, planning, control and increasingly sophisticated models capable of connecting language with physical action.
But saying that AI chips are automatically the biggest supply-chain bottleneck would be premature.
The semiconductor industry is enormous compared with today’s humanoid production.
The more interesting question is how the computing architecture of humanoids will evolve.
A robot that performs most inference locally requires substantial onboard computing and power.
A robot that relies more heavily on external infrastructure has different hardware requirements but introduces connectivity and latency considerations.
The balance between edge computing, onboard AI and external computing will influence everything from battery size to thermal management.
That architecture is still evolving.
The same is true of the software stack.
Physical AI may eventually become one of the most important parts of the humanoid system, but the machine still has to move through the physical world.
And physics does not care how impressive the software demonstration looks.
The Hidden Bottleneck May Be Quality
There is another constraint that receives much less attention than raw materials or AI chips.
Yield.
A factory can theoretically have enough components to build 10,000 robots.
That does not mean it can produce 10,000 working robots.
Figure’s manufacturing data demonstrates why.
The company reports more than 80% end-of-line first-pass yield and more than 50 inspection points during production. Each robot undergoes more than 80 functional verification tests before sign-off.
These numbers matter because humanoid robots are mechanically complex.
A small error in a conventional electronic product may result in a failed unit.
A small mechanical or calibration error in a machine with dozens of moving joints can create a system-level failure.
As production increases, quality control becomes an industrial science of its own.
The winning companies may therefore not necessarily be those with the fastest assembly line.
They may be those that can achieve the best combination of:
cycle time + yield + reliability + component consistency + cost.
That is a very different competition from the one shown on a demonstration stage.
Boston Dynamics Is Moving From Demonstration to Industrial Deployment
Boston Dynamics provides another important example.
The company has moved Atlas toward industrial deployment with Hyundai Motor Group.
And on September 21, 2026, Boston Dynamics announced the opening of a Robotics Metaplant Application Center at Hyundai’s Metaplant America in Georgia.
The facility is designed as a real-world training and testing environment for Atlas. The robots are being trained on manufacturing tasks including logistics and sequencing automotive parts before assembly.
Boston Dynamics and Hyundai say the program will expand toward component assembly, while Hyundai plans to deploy up to 25,000 Atlas robots across its global manufacturing network over the coming years and establish a U.S. production facility capable of producing 30,000 robots annually.
Those numbers should be understood as planned deployment and production capacity, not as today’s installed production volume.
That distinction is important.
But the industrial direction is clear.
The robot is moving from a research platform toward a manufacturing product.
And the first destination is exactly where the business case is easiest to understand: automotive production.
Factories are already structured environments.
They contain standardized workstations, predictable workflows, controlled access, known objects and extensive automation infrastructure.
A robot does not need to understand the entire world to become useful in such an environment.
It needs to perform a defined set of tasks reliably.
That may be a much more realistic path toward commercial scale than immediately placing humanoids everywhere.
Tesla Shows Another Manufacturing Model
Tesla’s approach demonstrates the importance of manufacturing infrastructure at an even larger scale.
The company has been installing dedicated Optimus production infrastructure, using its existing manufacturing capabilities as a foundation for a new robot production system.
The significance goes beyond Tesla itself.
An automotive company already understands high-volume assembly, factory automation, supplier qualification, batteries, motors, electronics and large-scale production engineering.
If those capabilities can be transferred successfully to humanoid robotics, the boundary between automotive manufacturing and robotics becomes increasingly difficult to define.
But installed capacity is not the same as production.
A factory can be designed for a certain output without being able to reach that output.
Component availability, equipment uptime, downtime, yield, tooling, workforce, software and quality systems all become constraints as production approaches the theoretical limit.
That is the industrial reality behind every ambitious production target.
So, Who Is Actually Building the Robots?
The answer is increasingly clear.
The robot manufacturers are only one layer.
Figure, Boston Dynamics, UBTECH, Tesla, Agility Robotics and others are designing and assembling complete systems.
But underneath them is another industry.
Nabtesco is producing precision reduction gears.
Nidec is developing motors and reducers.
Schaeffler is developing humanoid-specific actuators and strain-wave gearboxes.
Battery manufacturers are adapting their products for robotics.
Hundreds of specialized suppliers are producing sensors, bearings, electronics, castings, machined components, connectors and other parts.
Mining and refining companies supply the materials.
Machine-tool companies provide the equipment that manufactures precision components.
Semiconductor manufacturers provide the computing and control hardware.
Industrial automation companies provide many of the machines that make those components.
The humanoid robot is therefore less a single product than a convergence point for multiple industrial ecosystems.
The Race May Be Decided Before the Robot Reaches the Factory Floor
This is perhaps the most important implication.
If humanoid demand grows rapidly, the winners may not be determined solely by AI performance.
They could be determined by who has access to the right industrial capacity.
Who can secure enough motors?
Who can produce enough precision gearboxes?
Who can manufacture actuators with consistent quality?
Who can obtain the required magnets?
Who can qualify hundreds of suppliers?
Who can maintain acceptable yields?
Who can reduce the cost of each joint?
Who can manufacture batteries that deliver the required power without making the robot too heavy?
Who can scale semiconductor supply without allowing computing requirements to overwhelm the power budget?
And ultimately:
Who can turn a laboratory machine into a repeatable industrial product?
The Industrial System Behind the Robot
This changes the way the humanoid race should be understood.
The most visible competition is happening between robot manufacturers.
The less visible competition is happening between supply chains.
That competition involves technologies that have existed for decades as well as technologies that are still emerging.
The industrial robot companies of today may become important suppliers for tomorrow’s humanoid industry.
Automotive suppliers may find a new market for their motors, bearings, batteries and production technologies.
Machine-tool companies may benefit from demand for higher volumes of precision components.
Semiconductor companies may gain a new category of edge-computing customers.
Material processors may become strategically important simply because every additional robot adds another set of motors and magnets to global demand.
And countries that have spent decades building manufacturing ecosystems may find that their industrial infrastructure has suddenly become one of their greatest strategic assets.
The robot on the factory floor is only the visible part.
Behind it is a much larger machine.
It includes mines, refineries, chemical plants, steel mills, machine tools, semiconductor fabs, battery factories, component suppliers, logistics networks, software systems and thousands of engineers.
That machine is what has to scale.
The Question Is No Longer Whether Humanoids Can Be Built
The evidence from 2026 shows that humanoid robots are moving beyond isolated demonstrations.
Figure is scaling production.
Boston Dynamics is moving Atlas into real manufacturing environments.
Chinese manufacturers are building dedicated humanoid factories.
Established industrial suppliers are developing motors, actuators and precision gearboxes specifically for the new category.
Battery manufacturers are developing dedicated robotics products.
And the global industrial base is being pulled into the process.
But the same evidence also shows that the industry is not yet a mature mass-production ecosystem.
Supply chains are still being qualified.
Production yields are still improving.
Component architectures are still evolving.
Critical-mineral processing remains geographically concentrated.
And many of the technologies needed for humanoids must be adapted from other industries before they can support much larger volumes.
That leaves the industry at an unusual point.
The robots are becoming real before the supply chain behind them is fully mature.
And that may be the most important story of all.
The race to build humanoid robots is not simply a race between companies developing artificial intelligence and mechanical bodies.
It is a race to build an industrial system capable of producing those machines repeatedly, economically and reliably.
The companies that understand that distinction may have an advantage that is difficult to see in a product demonstration.
Because the ultimate question is not:
Who can build the most impressive robot?
It is: